Mathematics and Artificial Intelligence in Modern Finance
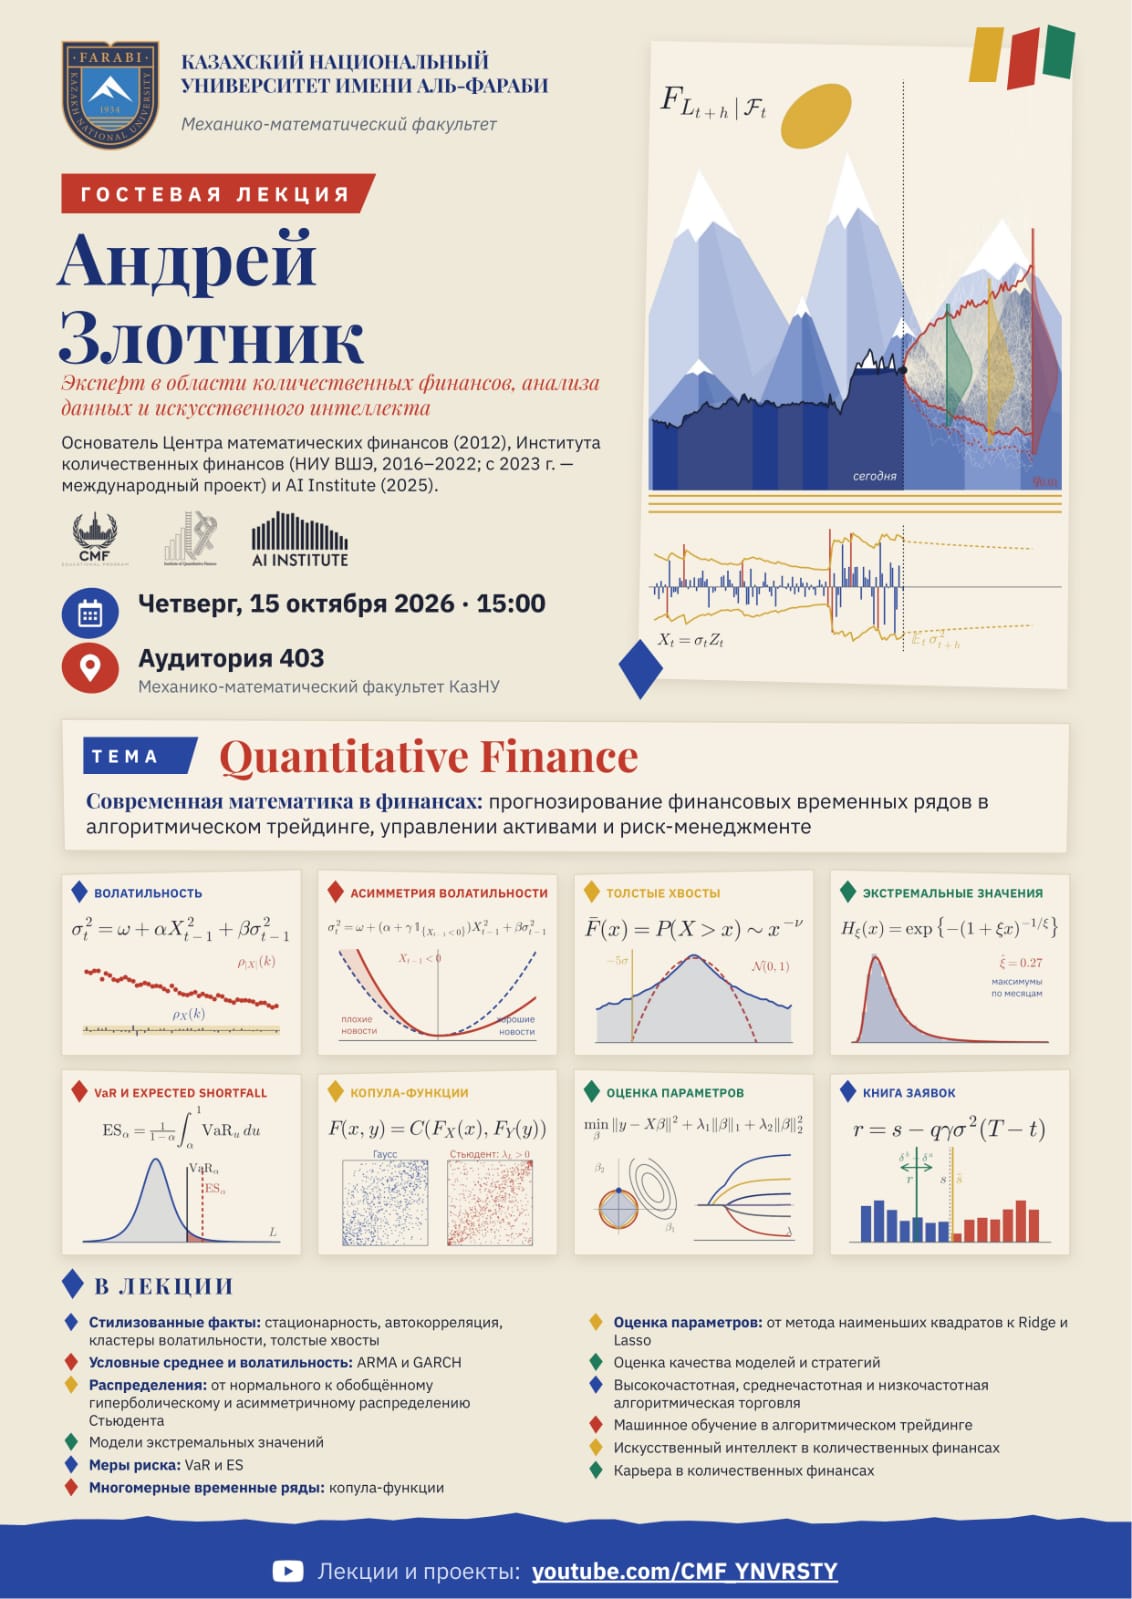
On October 15, 2026, a guest lecture entitled “Quantitative Finance” was held at the Faculty of Mechanics and Mathematics of Al-Farabi Kazakh National University. The lecture was delivered by Andrey Zlotnik, an expert in quantitative finance, data analysis, and artificial intelligence.
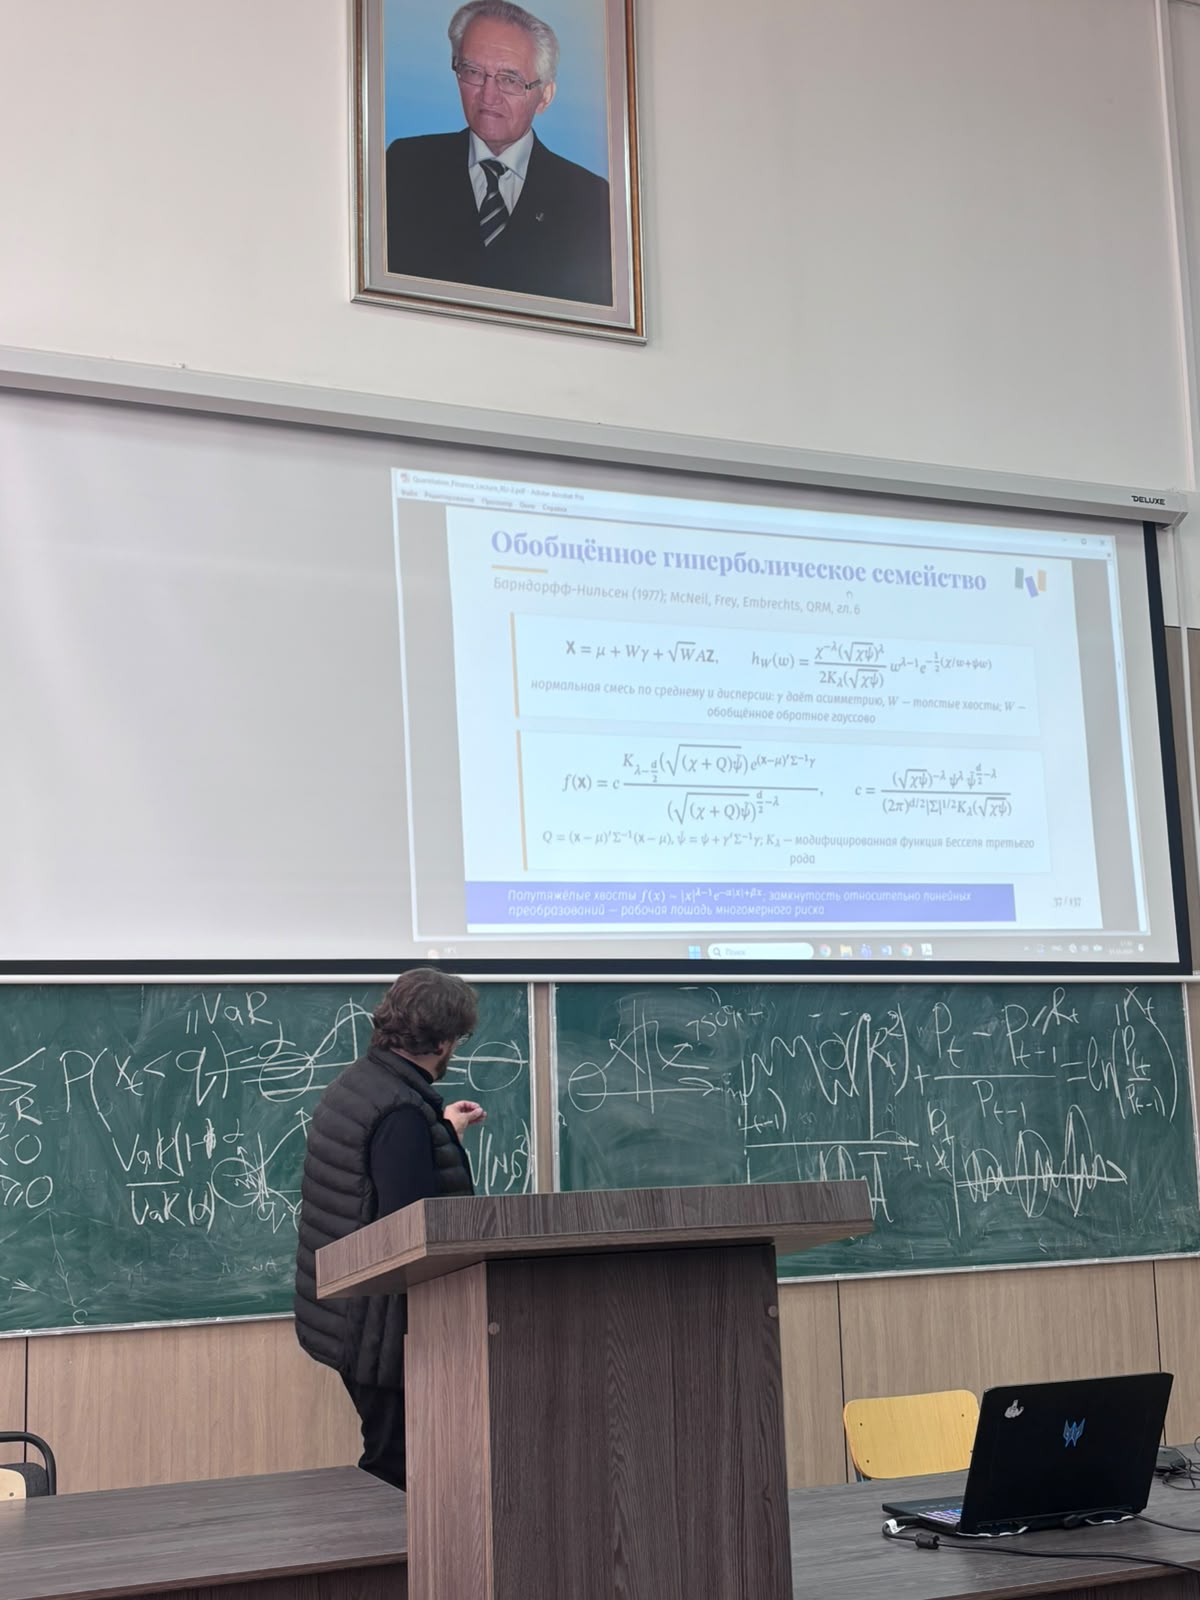
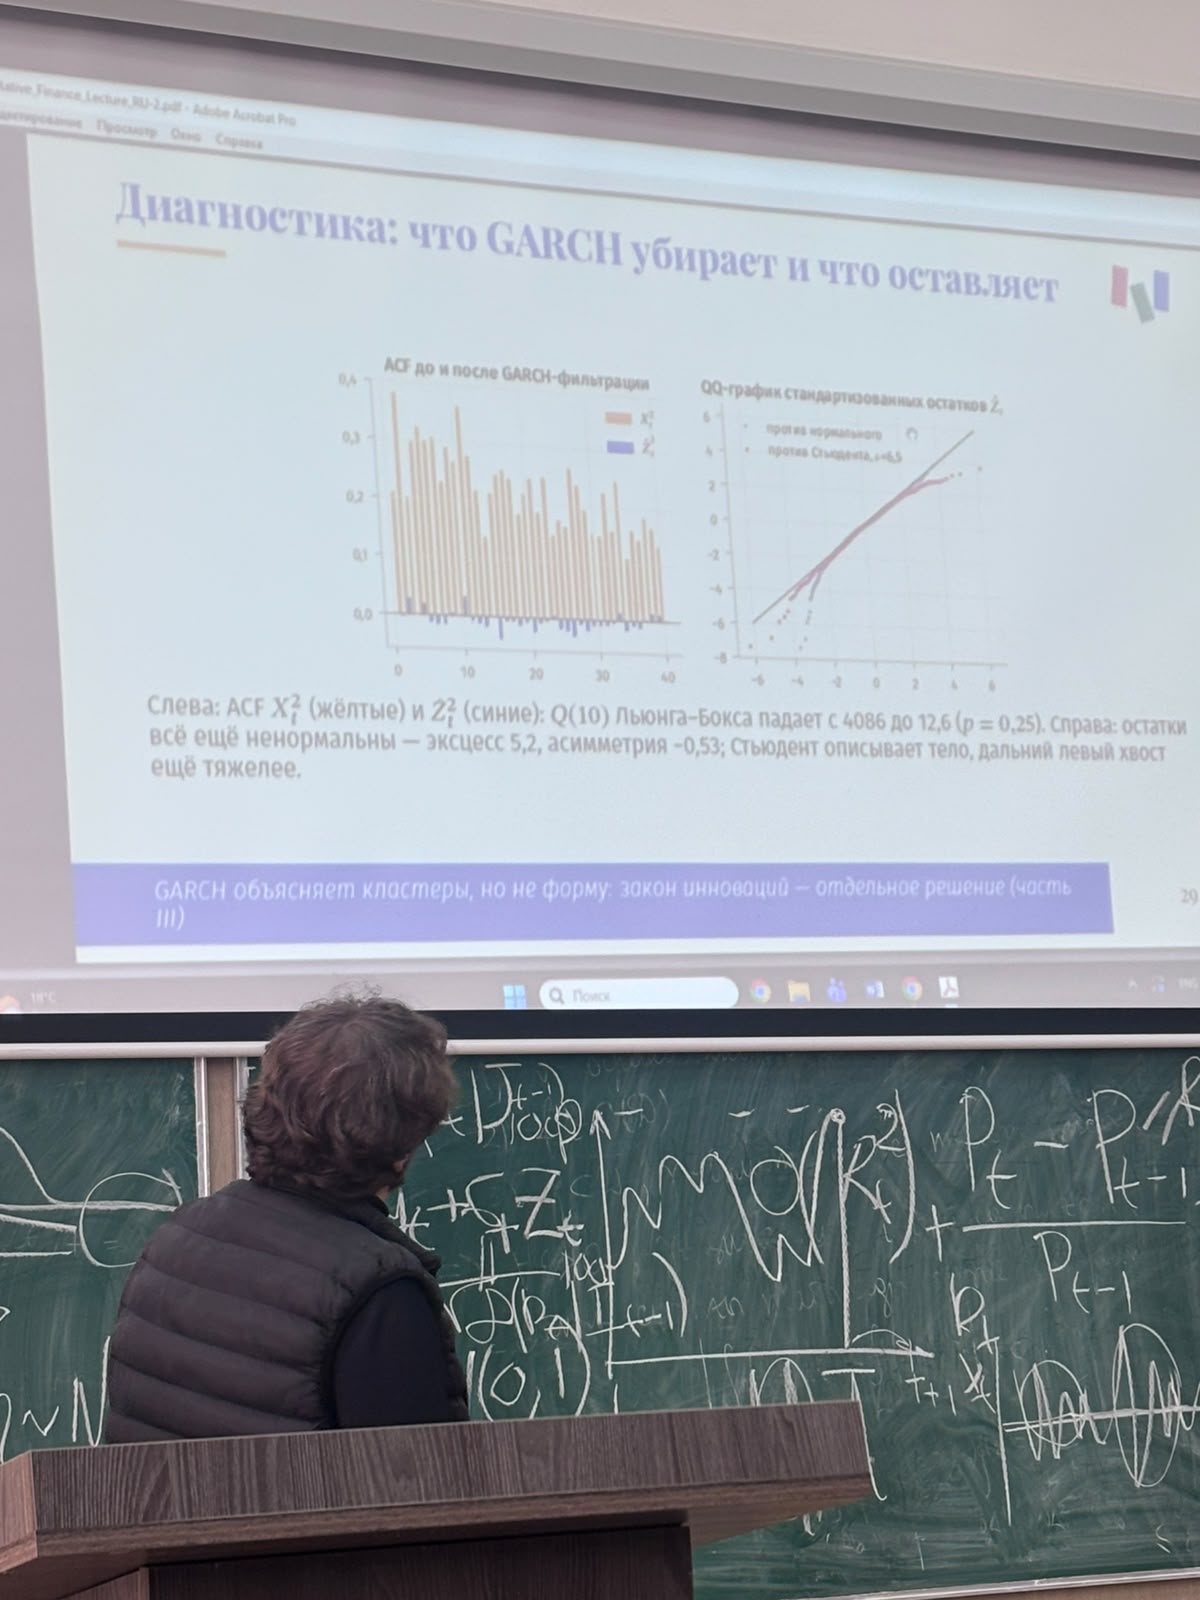
The lecture covered modern mathematical methods for analyzing and forecasting financial time series and their applications in algorithmic trading, asset management, and risk management. Particular attention was given to volatility modeling, GARCH models, fat-tailed distributions, extreme value theory, risk measures such as VaR and Expected Shortfall, copula functions, machine learning, and artificial intelligence in quantitative finance.
The lecture was delivered for 4th-year students of the “Computational Science and Statistics” educational program. The event provided students with an opportunity to expand their knowledge and explore practical applications of statistics, data analysis, machine learning, and mathematical modeling in modern finance.
Department of Computational Science and Statistics
Other news